Buyer Backed Out in Roseville: Do You Keep the Deposit?
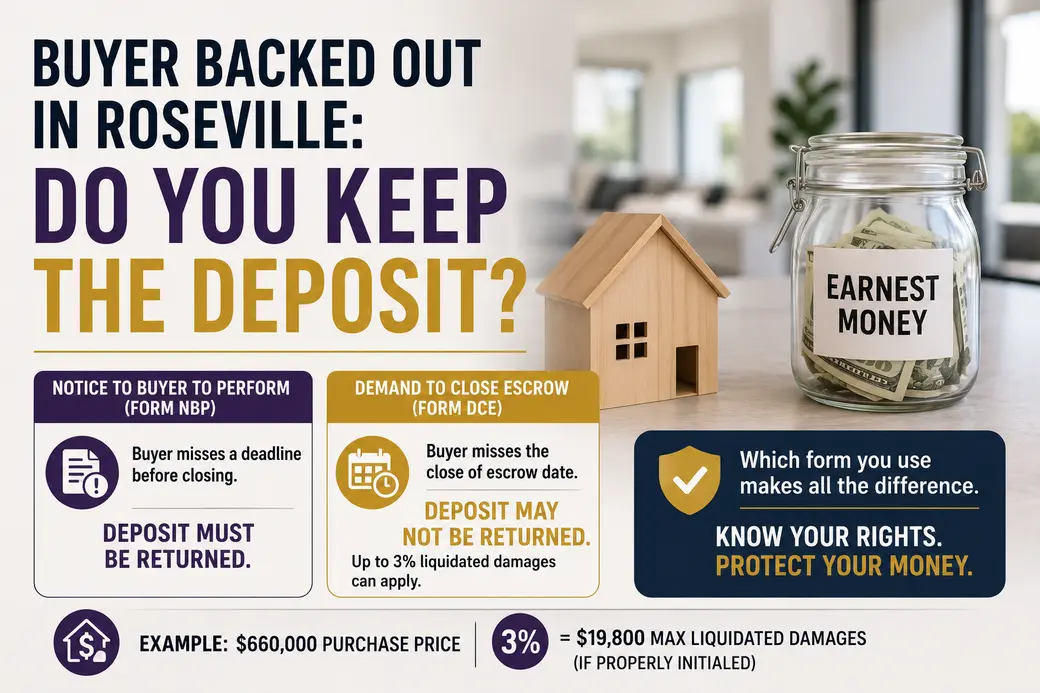
If a buyer backs out of escrow in Roseville, does the seller keep the earnest money?
Not automatically — and the answer turns on which C.A.R. form you use to cancel. If you cancel using a Notice to Buyer to Perform (Form NBP), the California Residential Purchase Agreement requires you to release the buyer's deposit back to them. If the buyer blows past the close-of-escrow date and you cancel after a Demand to Close Escrow (Form DCE), the deposit is not automatically returned, and liquidated damages of up to 3% of the purchase price can apply. On a $660,000 Roseville home, that ceiling is roughly $19,800 — and only if both parties separately initialed the liquidated damages paragraph.
By Rich & Kat Farless | August 30, 2026
The call usually comes on a Tuesday afternoon. The seller has already packed half the garage, signed a lease on a rental in Lincoln, and told the neighbors. Then escrow calls: the buyer is out.
About 5% of residential contracts terminate before closing nationally, and most of them die in the same two places — inspection and financing. That number feels abstract until it's your deal.
Here's what almost every Roseville seller gets wrong in the first 48 hours: they assume the deposit is theirs. It usually isn't. And the steps you take in that first week determine whether you keep any of it, how fast you get back on the market, and what you're legally required to tell the next buyer.
Let's walk through it.
The Form You Cancel With Decides Who Keeps the Money
This is the part nobody explains, and it's the single most expensive misunderstanding in a failed California escrow.
The C.A.R. Residential Purchase Agreement gives a seller two different cancellation paths, and they lead to opposite outcomes for the deposit.
Path one: the buyer misses a deadline before closing. They didn't remove the inspection contingency on time. They never wired the initial deposit. They blew the loan contingency date. You serve a Notice to Buyer to Perform (Form NBP), which gives the buyer 2 days after delivery to cure the problem.
The counting is stricter than most people expect. The day the notice is delivered is day zero. The next day is day one. If the second day lands on a Saturday, Sunday, or holiday, the buyer gets the next business day. You also can't serve an NBP more than two days before the buyer's deadline — no sending it early to apply pressure. If the buyer still doesn't perform, you may then cancel using Form CC, the Cancellation of Contract, Release of Deposit and Cancellation of Escrow.
And here's the catch: when you cancel down the NBP path, the RPA requires you to authorize release of the buyer's deposit. The form protects your right to walk away. It does not hand you the money.
Path two: the close-of-escrow date passes and the buyer hasn't closed. Different situation, different form. You serve a Demand to Close Escrow (Form DCE), which gives the buyer a minimum of 3 days from delivery — not from signing — to fund and close. If they still don't close, you can cancel.
Cancel down this path and the RPA does not automatically require you to return the deposit. This is the road where liquidated damages actually live.
Same failed deal. Same buyer. Two forms, two completely different outcomes. We've seen sellers hand back $18,000 they were entitled to argue for, simply because their agent reached for the wrong form on the wrong day.
One more precondition that catches sellers off guard: you have to be in full compliance with the contract yourself. If you never gave the buyer access to the property, you can't cancel because they failed to remove the investigation contingency. If you didn't let the appraiser in, you can't cancel over the appraisal contingency. The RPA won't let you create the failure and then collect on it.
The 3% Cap — and Why Most Sellers Never Collect It
Say you're on the DCE path and the buyer is genuinely in default. Now the ceiling comes into play.
Under California Civil Code § 1675, for a dwelling of four units or fewer that the buyer intended to occupy, enforceable liquidated damages are capped at 3% of the purchase price. Anything at or under 3% is presumed reasonable; above it, the seller has to prove the amount was reasonable.
What that looks like across the markets we serve:
Roseville, at a mid-2026 median around $660,000 — cap of roughly $19,800
Folsom or Lincoln, at $750,000 — roughly $22,500
El Dorado Hills, at a $1,081,000 average sold price — roughly $32,400
Granite Bay, at $1,500,000 — roughly $45,000
Those are ceilings, not checks. Four things stand between you and that number.
First, the clause has to have been signed correctly. Civil Code § 1677 requires the liquidated damages provision to be separately signed or initialed and set in at least 8-point boldface type. A surprising number of California deposit disputes turn on exactly this. If the paragraph wasn't initialed by both sides, the clause is unenforceable and your recovery drops to actual damages you can prove.
Second, you can't just take it. Escrow is a neutral stakeholder. Your title and escrow company cannot release a dollar without mutual written instructions from both parties, a mediator or arbitrator's decision, or a court order. Your belief that you're right has no effect on the wire.
Third, refusing to sign can cost you. Under Civil Code § 1057.3, a party who fails to execute the release documents within 30 days of a written demand can be liable for the funds, plus treble damages capped between $100 and $1,000, plus the other side's reasonable attorney's fees. There's an exception when the funds are withheld to resolve a genuine good faith dispute — meaning you had a reasonable belief you were entitled to hold them. "I'm angry and I'm not signing" is not a good faith dispute.
Fourth, you have to mediate first. Section 22 of the RPA requires the parties to attempt mediation before filing suit or arbitration. Skip it, or refuse a request to mediate, and you forfeit your right to recover attorney's fees even if you win — the rule confirmed in Lange v. Schilling. A 2025 appellate decision, Evleshin v. Meyer, softened this slightly: an initial refusal isn't necessarily fatal if you retract it and agree to mediate before the case is actually filed.
And suing for specific performance? Against a defaulting buyer, a specific performance claim ultimately produces a money judgment — you can't force someone to want your house. Between mediation, arbitration, and collection, the math on a $19,800 claim rarely favors the fight.
We're agents, not attorneys, and none of this is legal advice. When real money is on the table, a California real estate attorney is worth the consultation fee. But you should walk into that conversation knowing which form was served and whether the liquidated damages paragraph was initialed — because those two facts drive everything else.
Getting Back on the Market in Placer County Without Losing Momentum
While the deposit question grinds on, the clock is running on the thing that actually costs you money: carrying the house. Mortgage, taxes, insurance, and utilities on a Placer County home in the $500K–$1.5M range routinely run $3,000–$6,000 a month.
Three things to get right.
Time your relist. MetroList — the MLS covering Placer, Sacramento, and El Dorado counties — treats a listing reactivated within 30 days as Back on Market, with the cumulative history intact. A property has to sit off-market longer than that for a genuinely clean slate. A same-day relist accomplishes nothing except telling every buyer's agent in the region that something happened. Also worth knowing: if you intend to pursue damages, you generally shouldn't relist before the scheduled close-of-escrow date, which is one more reason to make the cancellation decision quickly rather than letting it drift.
Expect to disclose what the last buyer found. If their inspector found dry rot, a failing HVAC unit, or a septic problem, that's now a known material fact. California Civil Code § 1102.1 requires prior reports on the property to be disclosed to subsequent buyers before close of escrow, and courts have consistently held that material facts known to a seller and not reasonably knowable by a buyer can't be hidden. Sellers hate this. In practice it works in your favor — handing the next buyer the prior report, along with a bid or a completed repair, removes the exact leverage the last buyer used. Deals that fall apart over inspection findings in Loomis homes on well and septic systems almost always come back stronger when the seller gets ahead of the report.
Have a backup already signed. A C.A.R. Back-Up Offer Addendum (Form BUO) puts a fully signed offer in ranked second position. If the primary contract dies, backup #1 activates automatically at its own terms — no relist, no renegotiation, no gap. It is the single strongest asset a seller under contract can hold, and it costs nothing to accept.
The other half of the work is preventing a repeat. Before you accept the next offer, look past the number: verify the lender, the loan type, the down payment, and how much of the buyer's cash is actually liquid. A buyer whose financing structure you understand is worth more than one who offered $10,000 more with a preapproval nobody read. In the Granite Bay and Loomis luxury tier, that scrutiny matters even more, since jumbo loans carry tighter reserve and appraisal requirements that can unravel late.
And if the next buyer comes back asking for money after their inspection, you'll want to know whether a credit or a price reduction serves you better — because after one fall-through, the instinct to just cut the price is usually the more expensive reflex.
This is exactly the kind of situation we walk clients through before it becomes a crisis. Every deal is different, and the right move depends on which deadline was missed, what your paperwork actually says, and how much runway you have.
Frequently Asked Questions
Can the seller just keep the earnest money if the buyer walks away?
No. In California, escrow can only release the deposit with mutual written instructions from both parties, a mediator or arbitrator's decision, or a court order. Even when a seller has a strong claim, the money stays put until one of those three things happens.
How much earnest money can a Roseville seller actually keep?
For a residence of four units or fewer that the buyer intended to occupy, California caps enforceable liquidated damages at 3% of the purchase price — about $19,800 on a $660,000 Roseville home. The cap only applies if the liquidated damages paragraph was separately initialed by both parties and printed in 8-point boldface or larger.
What's the difference between a Notice to Buyer to Perform and a Demand to Close Escrow?
An NBP is used when a buyer misses an obligation before closing, such as removing a contingency, and gives them 2 days to cure. A DCE is used when the close-of-escrow date has already passed, and gives at least 3 days. Cancel via NBP and the RPA requires you to release the deposit; cancel via DCE and it does not.
Do I have to tell the next buyer why the first deal fell through?
You have to disclose known material facts about the property, which includes inspection reports and defects the prior buyer discovered. You don't have to narrate the buyer's personal financing troubles. The practical move is to hand the next buyer the prior report along with repair bids — it removes the surprise and protects your negotiating position.
How soon can I relist my home in Placer County?
You can relist immediately, but MetroList will show the listing as Back on Market with its cumulative history if it's reactivated within 30 days. If you're pursuing damages against the defaulting buyer, you'll generally want to wait until the scheduled close-of-escrow date has passed before putting it back on.
Where This Leaves You
A buyer backing out feels like a disaster, and financially it usually isn't — as long as you move quickly, cancel with the right form, and get back in front of buyers before the market forgets your listing. The deposit is worth fighting for only in specific circumstances. The carrying costs and the relist strategy matter every single time.
If your deal just fell apart, or you're weighing an offer and want a second set of eyes on the buyer's financing before you take your home off the market, Rich & Kat are here to help. Schedule a free consultation at richandkatsoldthat.com/talktous.
About Rich & Kat Farless
Rich and Kat Farless are a husband-and-wife real estate team with over 30 years of combined experience serving buyers and sellers across the Sacramento region. As the #1 husband-and-wife team in Roseville, CA, they specialize in single family, new construction, and luxury properties across Placer, Sacramento, and El Dorado counties. Connect with them at richandkatsoldthat.com.
Categories
- All Blogs (73)
- Buyer Guides (2)
- Buyers (1)
- Buying a Home (6)
- First-Time Buyers (2)
- Sellers (2)
- Buyer Resources (1)
- buyers (4)
- Buying (4)
- Buying a Home (14)
- Buying a Home, New Construction, Placer County, Roseville (1)
- California Process (1)
- California Real Estate (2)
- California Real Estate Process (10)
- Cost of Buying (2)
- Cost to Buy (2)
- Costs & Finances (5)
- El Dorado County (1)
- El Dorado Hills (1)
- Financing & Mortgages (3)
- First-Time Buyers (1)
- Folsom (2)
- Granite Bay (1)
- HOA (1)
- Home Buying (1)
- Home Financing (1)
- Home Prep & Pricing (1)
- Home Selling (3)
- Home Selling Tips (2)
- Lincoln CA (1)
- Loomis (2)
- New Construction (5)
- placer county (1)
- Real Estate Process (1)
- repairs (1)
- Roseville Real Estate (4)
- Seller Costs (2)
- Seller Resources (1)
- sellers (3)
- Selling (4)
- selling a home (11)
Recent Posts
Agent License ID: 01193836, 01186753
+1(916) 284-1520 | kat@homesbyrichandkat.com