VA Loans in Placer County, CA: What Veterans Need to Know
How do VA loans work in Placer County, CA in 2026?
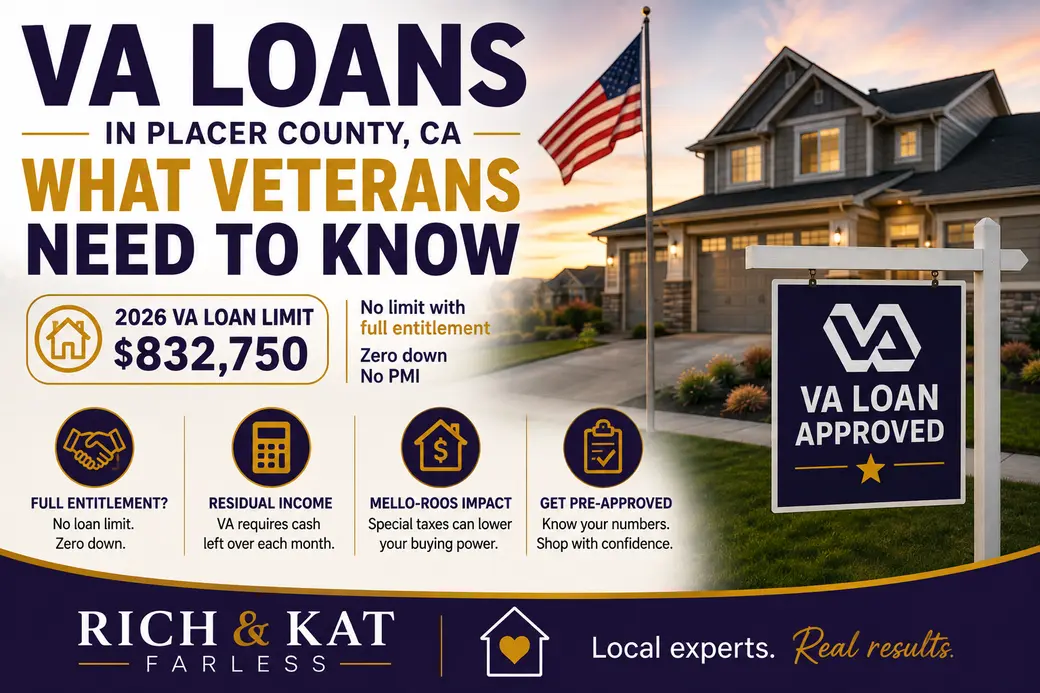
Placer County's 2026 VA loan limit is $832,750 — but that number only applies to veterans with partial entitlement. If you have full entitlement, there is no loan limit at all, and you can buy above $832,750 with zero down as long as your lender approves you. What actually caps most Placer County veterans isn't the loan limit. It's the VA's residual income test and local Mello-Roos special taxes, which together can pull $50,000 to $60,000 off your maximum purchase price in West Roseville, Lincoln, and Folsom Ranch.
By Rich & Kat Farless | August 21, 2026
Placer County's Veterans Services Office handled a record 21,491 requests last year, with more than 10,000 in-person visits — nearly double the year before. That's a lot of local veterans and military families sorting out benefits, and a lot of them are trying to figure out what their VA loan will actually buy in Roseville, Rocklin, Lincoln, Loomis, and Auburn.
Almost every article you'll find on this starts and stops at "zero down, no PMI, here's your county limit." That's the easy part. Here's the part that actually decides what you can buy.
The $832,750 Number Is Probably Not Your Limit
Placer County's 2026 conforming limit is $832,750. So is Sacramento County's, El Dorado County's, and Yolo County's. Every local lender page leads with it.
But the VA eliminated loan limits for veterans with full entitlement. If you've never used your benefit, or you sold your last home and paid off the VA loan in full, you have full entitlement — and there is no cap on what you can borrow with zero down. A veteran with full entitlement can buy a $1.4 million home in Granite Bay with nothing down if the lender's underwriting supports it. The county number never enters the conversation.
The $832,750 figure matters when you have partial entitlement — you already have a VA loan outstanding, or you had a prior VA loan that was assumed or went through a short sale without restoration. Then the math shifts: the VA guarantees 25% of the county limit minus what's already tied up, and you cover the gap with a down payment.
Two things veterans in this market get wrong constantly:
You can hold two VA loans at once. Second-tier (bonus) entitlement exists specifically for the PCS scenario — you're stationed at Beale, you get orders, and you need to buy at the new duty station before the Placer County house sells. As long as your remaining entitlement covers the 25% guarantee, you can carry both.
Restoration isn't one-and-done. If you sell the property and pay off the loan, you can restore your entitlement as many times as you want. The one-time-only restoration applies when you keep the property and pay off the loan some other way.
If your target price sits above the county limit and you're working with partial entitlement, it's worth comparing your options against jumbo loans in Granite Bay and Loomis before you assume the VA route is off the table. Usually it isn't.
What Actually Caps Your Buying Power: Residual Income and Mello-Roos
Conventional and FHA loans have one affordability test: debt-to-income. VA loans have two.
Residual income is the VA's second test, and it has no equivalent anywhere else. It's the cash left over each month after your full PITI payment, all your recurring debts, estimated taxes, and a maintenance-and-utilities figure the VA calculates at $0.14 per square foot. For the West region — that's us — a family of four on a loan above $80,000 needs $1,117 per month remaining.
That square-footage line catches people. A 2,400 square foot home in Winding Creek or Placer One triggers a $336 monthly deduction before you've paid a single bill. A 1,600 square foot Rocklin resale triggers $224. Same buyer, same income, $112 a month of difference in the qualifying math purely because of house size.
There's a second wrinkle specific to active-duty buyers. BAH is tax-free, and most lenders will gross it up when calculating your debt-to-income ratio. For residual income, the VA does not allow grossing up. Your BAH — $2,052 at Beale, for reference — counts at face value. Buyers who pre-qualify themselves using a DTI calculator and then get a smaller number from underwriting usually just ran into this.
And then there's the one that's genuinely local: Mello-Roos.
Most of the new construction inventory in this market sits inside a Community Facilities District. West Roseville — Fiddyment Farm, WestPark, Sierra Vista, Winding Creek, Amoruso Ranch, Placer One — plus Bickford Ranch in Lincoln and Folsom Ranch across the county line all carry CFD special taxes, commonly $2,500 to $4,500 a year.
That special tax is not a footnote. Lenders fold it into your housing expense for DTI and it reduces your residual income. A $300-a-month CFD can cut your maximum purchase price by $50,000 to $60,000. A veteran pre-approved at $750,000 on a resale in central Roseville may land closer to $690,000 on a new build two miles west — same income, same credit, different tax roll.
National VA content never covers this, because Mello-Roos barely exists outside California. Local Mello-Roos content never covers it, because it's written for conventional buyers. If you're weighing new construction, our breakdown of what a new construction monthly payment actually looks like in Roseville walks the same math from the other direction.
This is exactly the conversation we have with every veteran client before they walk a model home. Get the CFD number for the specific parcel — not the community average — and hand it to your lender before you write anything.
Two 2026 Rule Changes That Fixed the VA Buyer's Disadvantage
If your understanding of VA loans is more than a year old, two things changed and almost no local content has caught up.
The buyer-broker fee rule became permanent in April 2026. For decades, VA buyers were the only buyers in America who legally could not pay their own agent. After the NAR settlement removed guaranteed seller-paid commissions from the MLS, that turned into a real problem. The VA opened a temporary fix in August 2024 and made it permanent this spring. Veterans can now pay a buyer-broker fee directly, with three conditions: it has to be reasonable, it cannot be financed into the loan, and there must be a signed buyer-broker agreement in the loan file with the fee itemized on the Closing Disclosure. And when the seller pays it, that amount falls outside the 4% concession cap entirely.
Speaking of that cap — it's widely misread. The 4% limit applies to concessions, meaning extras: prepaid taxes and insurance, discount points, paying your funding fee. A seller paying your ordinary, allowable closing costs doesn't touch the 4%. So a well-structured VA offer can pull considerably more seller help than most listing agents assume.
The VA standardized its single-close construction loan process nationwide in August 2026. Builders no longer need a VA Builder ID; lenders vet them on licensing, insurance, and experience instead. In a county where the pipeline is Amoruso Ranch, Placer One, Winding Creek, and Bickford Ranch, that matters — though finding a lender who actually offers the product is still the hard part.
About sellers "not accepting VA offers"
You'll hear it. It's built on stale information.
VA appraisals run 7 to 14 business days and VA purchase loans close in roughly 40 to 45 days — right in line with conventional. The appraiser checks Minimum Property Requirements, which are about safe, sound, and sanitary, not cosmetic perfection. And if the appraiser thinks value may come in low, the Tidewater process gives your agent and lender a window to submit additional comparable sales before a number is issued. That's a safeguard conventional appraisals don't offer.
The termite myth is worth killing too. California treats a Wood Destroying Pests and Organisms report as standard, and VA transactions almost always require Section 1 clearance. But since VA Circular 26-22-11 in June 2022, the buyer may pay the inspection fee in any state. It's a negotiating item, not a seller mandate.
The local context helps here. Roseville's median sold price is running around $630,000, supply sits near two months, homes are trading at roughly 98–100% of list, and the share of listings taking a price cut jumped from 9.45% to 23.38% year over year. When nearly a quarter of the market is reducing price, a seller who declines a fully underwritten VA offer over a two-week appraisal is usually choosing another month on market. We say that to listing agents on our clients' behalf all the time, and it lands.
The Placer County Money Most Veterans Never Claim
Two benefits sit outside the loan itself, and they're worth more than the rate advantage for a lot of buyers.
The funding fee exemption. The 2026 funding fee is 2.15% of the loan on a first-use purchase with nothing down, 3.30% on subsequent use, dropping to 1.50% at 5% down and 1.25% at 10% down. On a $630,000 loan, first use at 2.15% is $13,545. If you receive VA compensation for a service-connected disability at any rating of 10% or higher, you're exempt. So are active-duty Purple Heart recipients and surviving spouses receiving DIC. Some veterans close without ever checking, and a refund claim afterward is a hassle.
The California Disabled Veterans' Property Tax Exemption. This one is a state benefit administered by your county assessor, and it has nothing to do with which loan you use. It's for veterans rated 100% disabled — or compensated at the 100% rate due to individual unemployability — for a service-connected condition, and for qualifying surviving spouses. For 2026 it reduces assessed value by $180,671 on the basic exemption, or $271,009 on the low-income exemption if household income falls under roughly $76,235. At Placer County's effective rate near 1.1%, that's about $1,987 to $2,981 a year off your tax bill.
You claim it on Form BOE-261-G, filed with the Placer County Assessor (530-889-4300). The basic exemption is a one-time filing as long as you keep qualifying. The low-income version has to be re-certified annually by February 15. Sacramento County and El Dorado County run the same form through their own assessors.
Worth knowing: if your assessed value is out of step with what the home is actually worth, the exemption and a Proposition 8 appeal are separate tracks and you can pursue both. We've covered appealing your Placer County property tax assessment in detail.
One more option to put on the table — CalVet. It's a state program funded through tax-exempt bonds, structured as a land contract where the state holds legal title until payoff, and it bundles in life and disability coverage. CalVet reaches up to $1,209,750 in high-cost California counties and will finance property types VA won't touch, including mobile homes and farms. For an acreage buyer in Loomis or Penryn, that's a real alternative. For most Placer County buyers, VA still wins on flexibility — but you should see both quotes.
If you want to see how the VA route stacks up against the other two loans most buyers here are weighing, start with how FHA and conventional loans compare in Roseville.
Frequently Asked Questions
What is the VA loan limit in Placer County for 2026?
$832,750 — the same as Sacramento, El Dorado, and Yolo counties. But that limit only applies to veterans with partial entitlement. With full entitlement there is no VA loan limit anywhere in California, so you can buy above that figure with zero down if your lender approves the loan.
Can I use a VA loan on new construction in West Roseville or Lincoln?
Yes. The VA standardized its single-close construction loan process nationwide in August 2026, and builders no longer need a VA Builder ID. Just get the exact Mello-Roos special tax for your specific parcel before you go under contract — that annual CFD charge counts against both your debt-to-income ratio and your VA residual income, and it can move your approved price by $50,000 or more.
How long does a VA loan take to close in the Sacramento area?
Roughly 40 to 45 days, comparable to a conventional loan. The VA appraisal itself typically takes 7 to 14 business days. If the appraiser believes value may come in below the contract price, the Tidewater process gives your agent and lender an opportunity to submit additional comparable sales before the final value is issued.
Do I have to pay for the termite inspection with a VA loan in California?
California transactions almost always involve a Wood Destroying Pests and Organisms report, and VA loans generally require Section 1 clearance before funding. Since VA Circular 26-22-11 took effect in June 2022, the buyer is permitted to pay that inspection fee in any state — so it's a negotiating point between you and the seller, not an automatic seller cost.
Can I rent out a home I bought with a VA loan in Roseville?
You have to move in within 60 days of closing and occupy the home as your primary residence, and most lenders expect at least 12 months of occupancy. After that, renting it out is generally permitted. What you cannot do is use a VA loan to buy a pure investment property from the start.
Does a VA loan work for a condo in Placer County?
Only if the project itself is VA-approved — it's a project-level review, not a borrower-level one. California has roughly 11,861 approved condo projects, searchable for free through the VA. Getting an unapproved project reviewed takes 60 to 90 days minimum, and rental bans, right-of-first-refusal clauses, or super-lien language in the CC&Rs will stop approval outright.
Your VA benefit is worth more in this market than most veterans realize — and the parts that decide your actual buying power are the parts nobody puts on a landing page. The county limit is rarely the constraint. Residual income, the Mello-Roos number on your specific parcel, and how your offer is structured are.
With over 30 years of combined experience across Placer, Sacramento, and El Dorado counties, we've walked a lot of military families through exactly this — including the conversations with listing agents who still think a VA offer is a risk. If you're ready to talk through your situation, whether you're PCSing in, separating, or finally using a benefit you've had for years, Rich & Kat are here to help. Schedule a free consultation at richandkatsoldthat.com/talktous.
About Rich & Kat Farless
Rich and Kat Farless are a husband-and-wife real estate team with over 30 years of combined experience serving buyers and sellers across the Sacramento region. As the #1 husband-and-wife team in Roseville, CA, they specialize in single family, new construction, and luxury properties across Placer, Sacramento, and El Dorado counties. Connect with them at richandkatsoldthat.com.
This article is general information about loan programs and California property tax exemptions, not lending, tax, or legal advice. Loan terms, entitlement calculations, and exemption eligibility depend on your individual circumstances — verify with your lender, a tax professional, and your county assessor.
Categories
- All Blogs (73)
- Buyer Guides (2)
- Buyers (1)
- Buying a Home (6)
- First-Time Buyers (2)
- Sellers (2)
- Buyer Resources (1)
- buyers (4)
- Buying (4)
- Buying a Home (14)
- Buying a Home, New Construction, Placer County, Roseville (1)
- California Process (1)
- California Real Estate (2)
- California Real Estate Process (10)
- Cost of Buying (2)
- Cost to Buy (2)
- Costs & Finances (5)
- El Dorado County (1)
- El Dorado Hills (1)
- Financing & Mortgages (3)
- First-Time Buyers (1)
- Folsom (2)
- Granite Bay (1)
- HOA (1)
- Home Buying (1)
- Home Financing (1)
- Home Prep & Pricing (1)
- Home Selling (3)
- Home Selling Tips (2)
- Lincoln CA (1)
- Loomis (2)
- New Construction (5)
- placer county (1)
- Real Estate Process (1)
- repairs (1)
- Roseville Real Estate (4)
- Seller Costs (2)
- Seller Resources (1)
- sellers (3)
- Selling (4)
- selling a home (11)
Recent Posts
Agent License ID: 01193836, 01186753
+1(916) 284-1520 | kat@homesbyrichandkat.com